6 October 2023
Chartwell Funding have enhanced their approach to protection – could you benefit by copying it?
Chartwell Funding is a successful firm based in Yate, just outside Bristol.
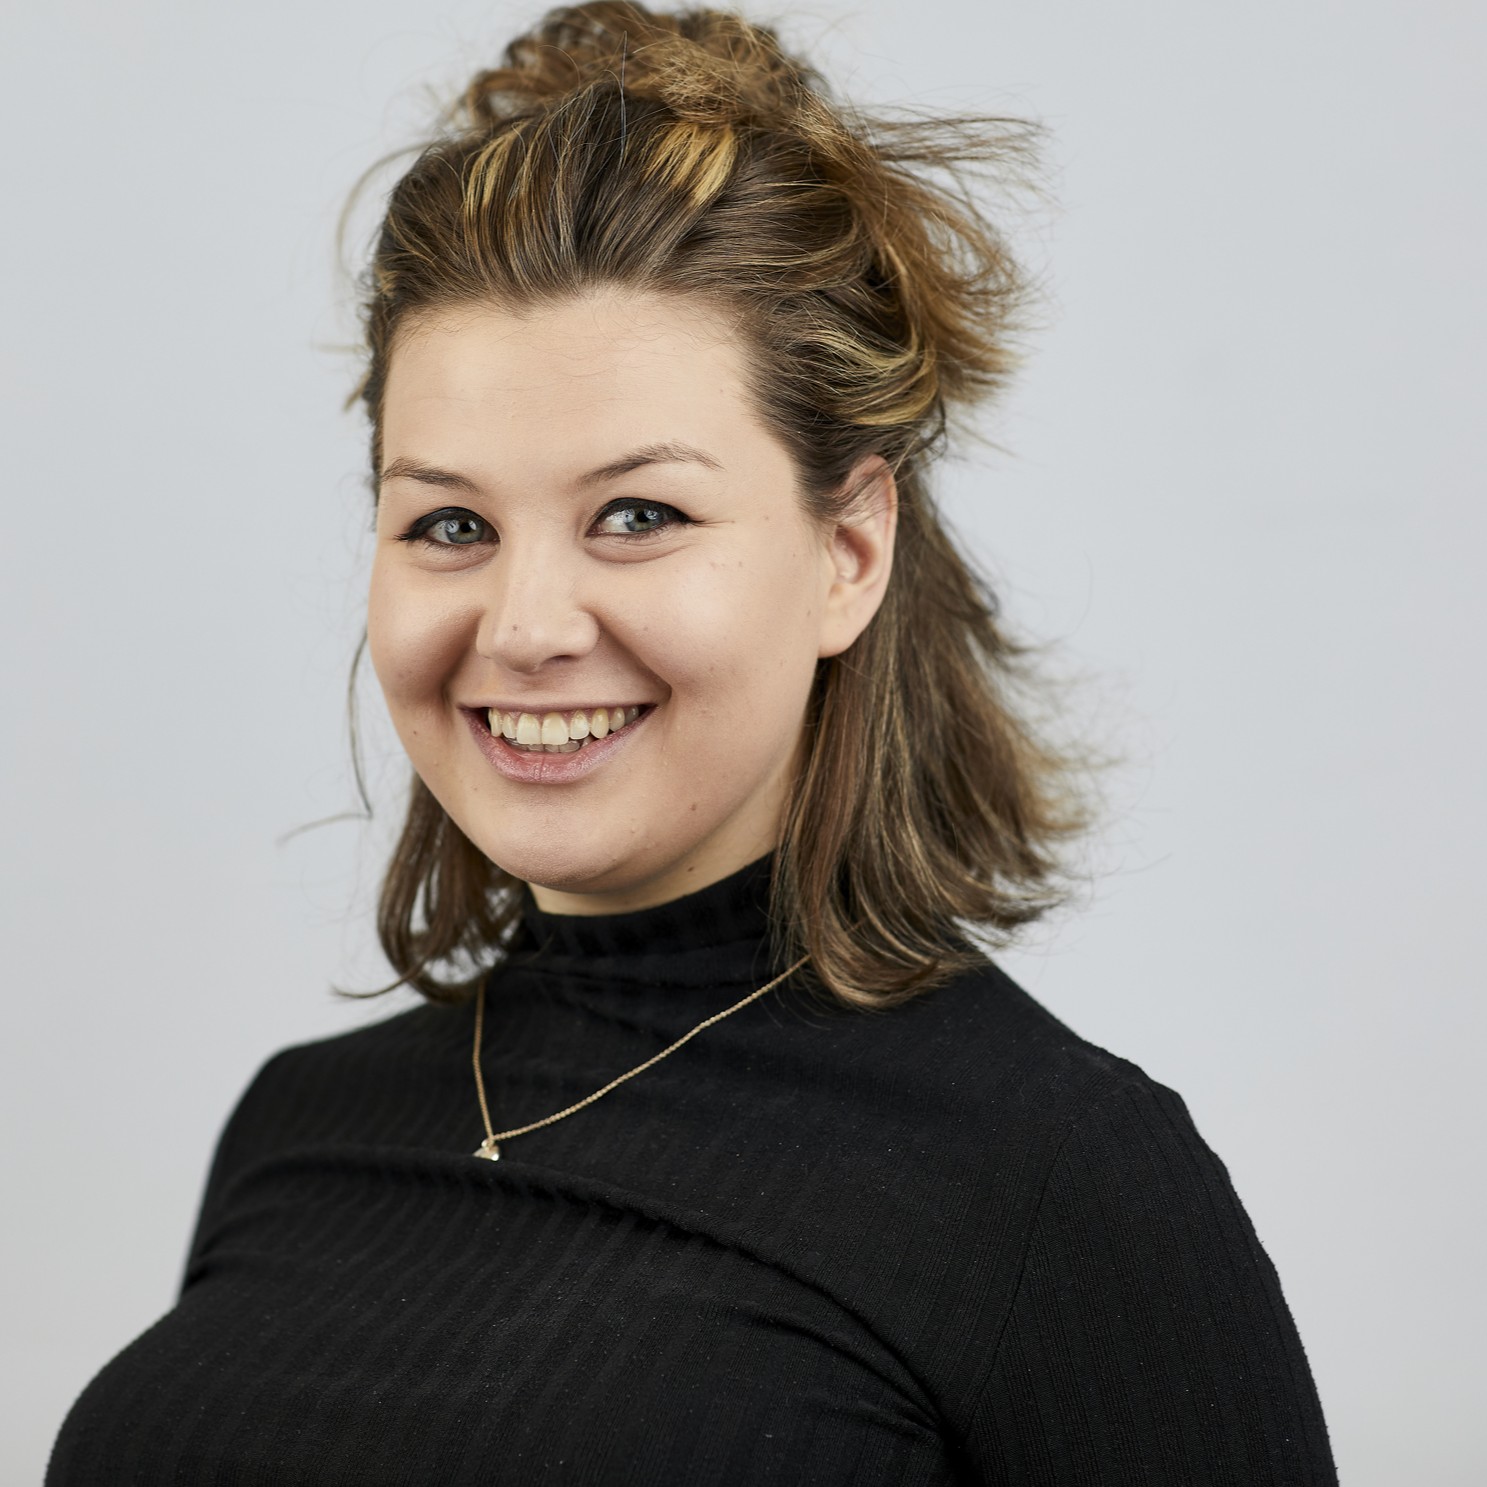
As part of our #TogetherWeProtect activity for 2023, we sat down with Mark Searle, Director at Chartwell Funding, to learn about their approach to protection and share how everyone – whether you’re a sole-trader or a larger firm – can learn from their success.
Mark, tell us a little about Chartwell.
We were established in early 2007 and have navigated the financial market’s various ups and downs since then.
We now boast a team of 16 advisers, with three exclusively advising on protection, and another three who are cross-trained and do both mortgages and protection.
Why do you have protection-only advisers?
As a business we’ve invested in those protection-only advisers because it’s so difficult to be an expert in everything – the volume of knowledge you need to have is simply incredible – that it’s inevitable you’ll miss opportunities.
We first recruited a protection-only role in 2019, and at the time their role was to look purely at missed opportunities. At that point, all our advisers had protection permissions, but none of them were protection experts.
And this new hire knew everything there was about protection products, and this knowledge meant her customers often took up two or three products. Straight away, we started writing £15k of business per month, just on the bits and pieces that our advisers had missed.
This opened our eyes and sent the business in a new direction, with a new bar set in terms of what advisers could achieve. From there, we offered our team the choice to either cross-train and do both protection and mortgages, or stick to mortgages and earn a fee for every protection referral they sent across. Most opted for the latter option, and we supported the ongoing training and development of those who opted to upskill.
Why focus on protection now?
Protection has always been on the radar – from a commercial point of view, we knew we couldn’t reach the levels we wanted to without it. And from a moral standpoint we weren’t having the right conversations with customers, because we were too busy doing mortgages, and that’s wrong.
It took us a long time to find the right person to write protection cases, but we’re now very glad we did.
What sets Chartwell up for success?
We believe knowledge is power. We do a huge amount of training; each week our protection advisers sit with insurers to get updates on products, and attend webinars, using all the tools at their disposal.
The more knowledge you have on a product, and the more we know about the customer’s circumstances and needs, the more confident we become with identifying what a customer needs and explaining it to them.
If you lack that knowledge, you tend to lean on the simpler products.
Is it worth it?
The hardest part of any mortgage business is getting leads. Once we’ve got them, we need to make the most of them – because if we don’t, we need to go out and find more and more mortgage leads – which in itself can cost money, whether in marketing or business development.
But if we maximise those relationships we already have, we can turn what would have been worth £1,000, and increase that by half or even double it.
We’re now more than three years into our journey; in 2022 we submitted £390,000 of protection business. This year we’re aiming for £500,000. And a lot of this is from leads we already have.
It’s not all plain sailing through. It’s taken a year to refine the model – when to pass it across, how to pass it across, what we say, and how we build the conversation through the fact-finds and mortgage planner, so it’s not a surprise when we start talking about it at application.
What advice would you give a sole-trader or very small firm?
If you’re a ‘one-man band’, you need to make a decision, as an individual, whether you want to put in the time and effort to understand protection and get it right, or whether you want to refer the business out to someone else – especially since Consumer Duty means the onus is on you to ensure customers are protected against foreseeable harm.
In fact, we do a lot of protection work for another mortgage broker who refers all their cases across. This can work really well as long as you trust each other and know what they’re doing at their end.
If yours is a smaller firm – say, there’s three of you writing 10 mortgages a month each – you could take on a protection adviser and they’d be kept busy enough, because we assume that everyone will at least have the conversation with a protection adviser. For every 10 mortgages, we expect to write four protection cases, each with at least two products per case – generating an additional £1,000-£1,500.
And because each case is less time-intensive for the adviser, you only need one protection adviser for every three mortgage advisers. It’s the most profitable part of our business.
And, finally, any advice for larger firms?
Firstly, don’t make assumptions about what others are willing to spend. Nine times out of ten, you get it wrong – you don’t know what they’ll want to protect or how much they’ll spend to do so.
Secondly, look at what products your customers are buying off you. Ask yourself where the shortcomings are. Are you selling enough income protection? Is it too reliant on life? Is it too much about the simple products? What about people with impaired health?
Look at both what you’re currently recommending, and what your customers are actually buying. If there’s not a good spread or your income protection levels are low, it’s time to look at investing in training or bringing a protection expert in-house.
--
Thank you Mark! Plenty of food for thought there. You may be inspired to up your protection game, or have decided to keep things simple and refer these cases to an expert.
If it’s the latter, we’ve partnered with some of the UK’s leading protection firms to create a referral solution you can trust – with referral income available for every customer who goes on to buy a protection product.
Content correct at the time of publication
Find out more